
This is a financial law. Section 139E is part of the federal tax code, and it decides whether benefits your tribe provides count as taxable income for your members.
Can your tribe give members a ceremonial benefit, like regalia, a feast, or an honorarium for taking part in a ceremony, without it counting as taxable income? In many cases, yes. That is the heart of the Tribal General Welfare Exclusion Act of 2014, and it is the subject of this four-week series from Potawatomi Life.
What the law says
Congress passed the Act in 2014 and added Section 139E to the Internal Revenue Code. It says that Indian general welfare benefits are not counted as gross income for tribal members, or their spouses and dependents. In December 2025, the Treasury finalized regulations that explain how it works.
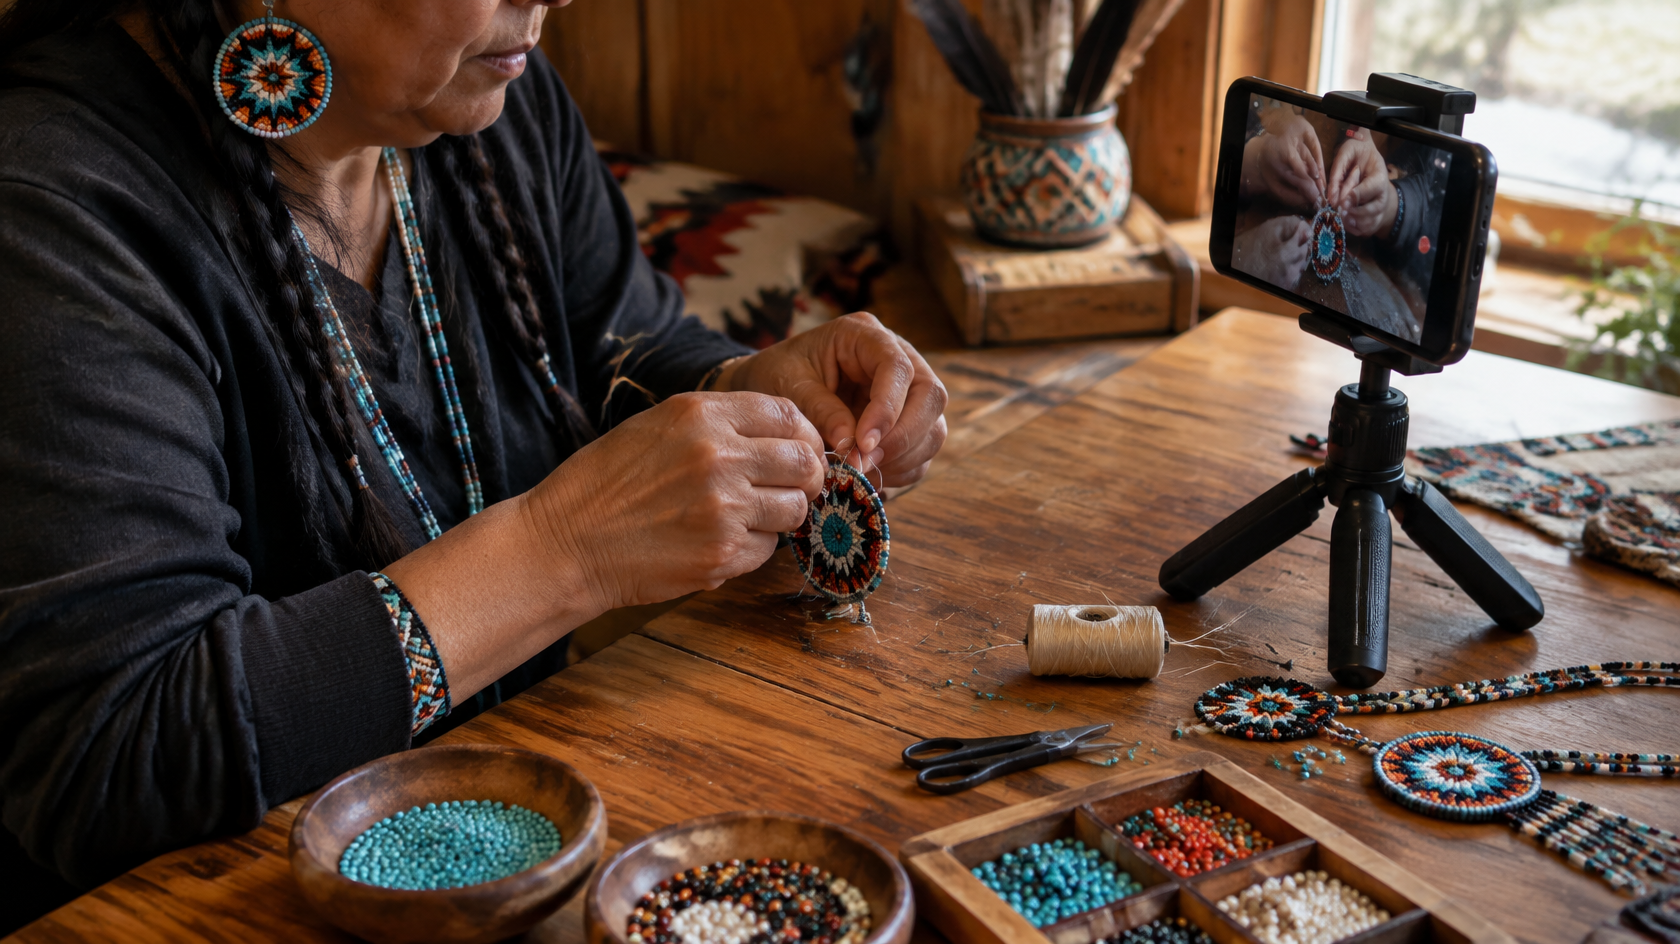
The Act also speaks directly to ceremony. Items of cultural significance, reimbursement of costs, and cash honorariums for taking part in cultural or ceremonial activities for the transmission of tribal culture are not treated as payment for services.
Why the council’s decision matters
Your tribal government decides what counts as general welfare, and the IRS defers to that decision. For ceremonial benefits, your tribe also decides what counts as a cultural or ceremonial activity. That authority is real, but it only protects your members if the board documents its decisions.
Coming up
Next week: what counts as ceremonial, and how to define it in writing. After that: honorariums versus pay for services. Then records, conflicts, and a board checklist.
This is general education, not legal or tax advice. Have a tribal tax attorney review any program.
Federal citations
- Tribal General Welfare Exclusion Act of 2014, Pub. L. 113-168, 128 Stat. 1883
- 26 U.S.C. 139E, including subsection (c)(5)
- 26 CFR 1.139E-1
- 90 Fed. Reg. 58378 (December 16, 2025)

Leave a Reply